AI & Automation
AI Chatbots for Mortgage Websites: Capture and Convert More Borrower Inquiries
A clear look at mortgage website chatbots: useful jobs, risky ones, how human handoff should work and when a well-built contact form is the better choice.
By Mortgage Site Pros Editorial Team · Published · Updated
A mortgage AI chatbot is a website assistant that answers general questions in conversation and helps a visitor reach a loan officer. At its best it captures an inquiry after hours, answers questions like what documents are typically needed, and books a call. At its worst it invents rate quotes, implies approvals and collects sensitive data it should never touch.
This guide covers both sides. You will see what jobs suit a chatbot, which ones should stay off-limits, how human handoff should work and when a fast, simple contact form does the job better. Our position is straightforward: a chatbot is an optional layer that needs scoping, guardrails and compliance review; it is not a requirement for a strong mortgage website.
For broader context, read AI for mortgage loan officers and mortgage lead follow-up, and see the loan officer marketing guide.
What can a mortgage chatbot do well?
Good chatbot jobs are general, factual and handoff-oriented.
- Answer general questions using approved content: what is pre-approval, what an FHA loan is, how to start.
- Collect basic contact details and the reason for the inquiry, with clear consent language.
- Offer to book a call on the loan officer’s calendar.
- Point visitors to relevant website pages, calculators or articles.
- Capture inquiries outside business hours and set expectations about when someone will reply.
What a chatbot should never do
These guardrails should be written into its configuration and tested.
| Off-limits behavior | Risk | Safer alternative |
|---|---|---|
| Quote rates or payments | Inaccurate quotes and advertising disclosure issues | Offer to connect with the loan officer |
| Say a visitor qualifies or is approved | Implied eligibility decisions | Explain next steps for a real pre-approval |
| Collect SSNs, account numbers or full income details | Data security and privacy obligations | Direct to the secure application system |
| Give legal or tax advice | Unlicensed advice | Recommend a qualified professional |
| Pretend to be a human | Trust and potential disclosure concerns | Identify itself as an automated assistant |
Chatbot or contact form?
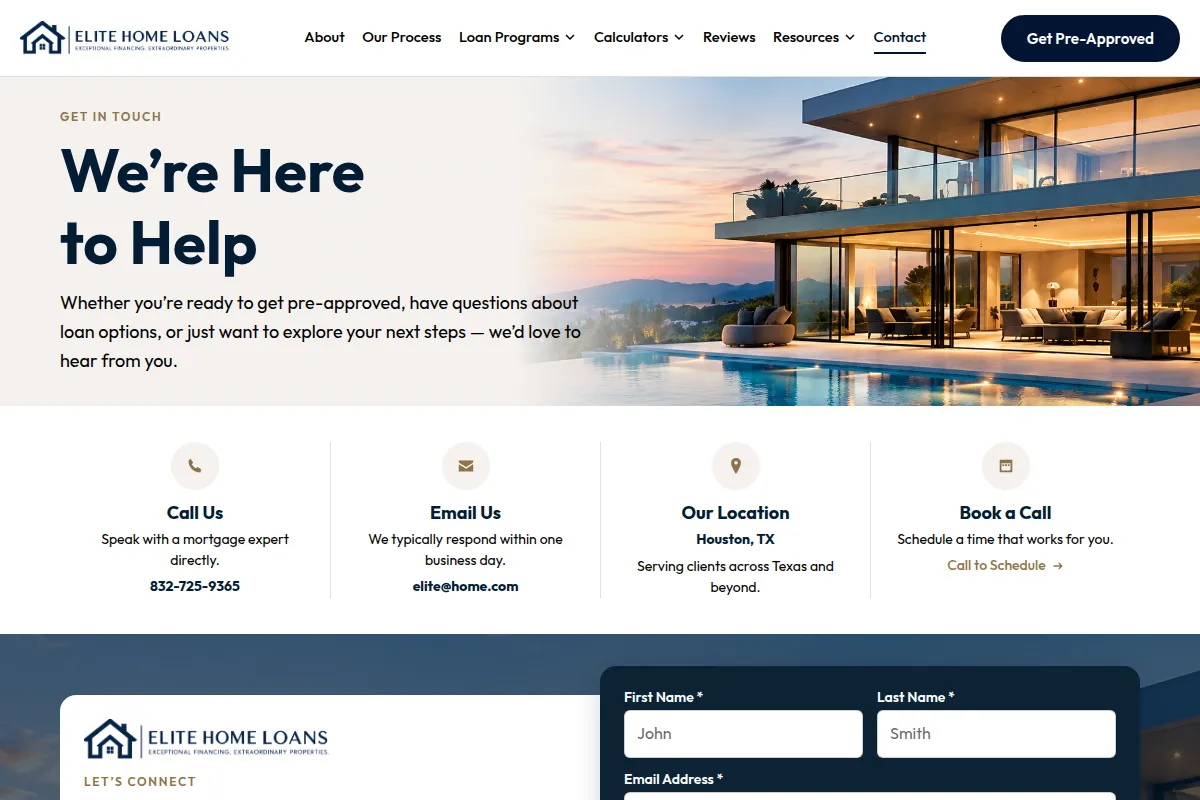
For many loan officers, a short contact form, a tappable phone number and a fast human response outperform a chatbot in simplicity and risk. Chatbots add scripts that can slow pages, need ongoing tuning, and must be monitored. The image below is a real contact form from a Mortgage Site Pros template. It is a form, not a chatbot, and it is included to show the simpler baseline any chatbot must beat.
| Factor | Contact form | AI chatbot |
|---|---|---|
| Setup effort | Low | Moderate to high: content, guardrails, testing |
| Risk of inaccurate answers | Very low | Requires guardrails and monitoring |
| After-hours capture | Yes, with an expectation message | Yes, plus answers to general questions |
| Page speed impact | Minimal | Depends on the script |
| Ongoing maintenance | Low | Review transcripts and update content regularly |
Designing the human handoff
The handoff is where chatbots win or lose. A visitor who asks a real question deserves a real person quickly.
- Offer handoff early: a talk to a loan officer option should be visible throughout.
- Pass the transcript and contact details into your CRM with source and consent recorded.
- Notify the loan officer immediately and create a follow-up task.
- Tell the visitor honestly when to expect a reply.
- Review transcripts weekly to improve answers and spot risky questions.
Compliance and privacy considerations
Chat transcripts are records of consumer communication and may contain personal information. Decide with your company where transcripts are stored, who can access them and how long they are kept. If the chatbot collects phone numbers for texting, consent language must be clear and approved; see the FCC guidance on texts. Fair lending policies apply to automated conversations too, so the bot must answer consistently and must not steer visitors.
Accessibility matters as well. Chat widgets should be keyboard operable and usable with screen readers; WCAG is the reference standard.
Writing the chatbot knowledge base
A chatbot is only as reliable as the content behind it. Rather than letting a general model answer freely, configure it to answer from an approved knowledge base and to hand off when a question falls outside it.
Build that knowledge base from content you already publish and that compliance has reviewed: program explanations, process pages, FAQs and office information. Keep answers general. For example, the bot can explain what pre-approval usually involves in your process, but it should not estimate what a particular visitor might qualify for.
- List the twenty questions borrowers ask most and write approved answers.
- List the questions the bot must always hand off: rates, eligibility, specific scenarios, complaints.
- Add a fallback response that offers a call or form when it is unsure.
- Date the knowledge base and review it whenever programs or policies change.
- Test with realistic and adversarial questions before launch, such as can you guarantee I will be approved.
Questions to ask a chatbot provider
If you evaluate a provider, ask for demonstrations rather than assurances.
| Question | Why it matters |
|---|---|
| Can answers be restricted to our approved content? | Reduces invented or inaccurate responses |
| How are transcripts stored, and for how long? | Privacy and record-keeping obligations |
| How does handoff to our CRM work? | Leads must reach a person with context |
| Is the widget keyboard and screen reader accessible? | Accessibility for all visitors |
| What is the page speed impact? | Slow pages lose visitors |
| How are SMS consent and opt-outs handled? | Messaging compliance |
Ownership and testing before launch
A chatbot without an owner degrades quickly. Assign three roles before it goes live: a content owner who maintains approved answers, a compliance reviewer who signs off on the knowledge base and consent language, and a response owner who receives handoffs and replies to visitors.
Then test like a skeptical borrower would. Run a scripted set of questions on desktop and phone, after hours and during business hours, and confirm the handoff reaches the CRM with the transcript attached.
- Ask for a rate quote and confirm the bot declines and offers a conversation.
- Ask whether you will be approved and confirm it explains next steps without implying a decision.
- Try to enter a Social Security number and confirm the bot discourages it and points to the secure application.
- Request a human and time how long the notification takes to reach the response owner.
- Type STOP after giving a phone number and confirm the contact is marked opted out.
- Navigate the widget with only a keyboard.
- Check page load on a phone before and after the widget is added.
A careful rollout plan
If you decide a chatbot is worth it, roll it out in stages.
- Write an approved knowledge base from your own website content.
- Configure guardrails from the off-limits table and test with tricky questions.
- Launch on one page, such as contact, before sitewide.
- Review transcripts weekly for the first two months.
- Compare inquiry quality against the form, not just volume.
Where Mortgage Site Pros fits
Mortgage Site Pros websites ship with contact forms. A chatbot is an integration option we can discuss and scope with you, including which provider, how handoff to your CRM would work and what compliance review is required. It is not included or live by default. Contact us to talk it through, or compare plans.
Frequently asked questions
Do mortgage websites need an AI chatbot?
No. Many loan officers do well with a short contact form, tappable phone and fast follow-up. A chatbot can help with after-hours questions if it is configured with guardrails and monitored.
Can a chatbot give rate quotes?
It should not. Rates depend on a full borrower scenario and rate advertising carries disclosure requirements. Configure the bot to offer a conversation with the loan officer instead.
Is chatbot data secure?
That depends on the provider and configuration. Never let a chatbot collect Social Security numbers or account details; send borrowers to the secure application system and agree retention rules with your company.
Should the chatbot say it is automated?
Yes. Identifying the assistant as automated sets honest expectations and builds trust. Ask your compliance team about any specific disclosure requirements.
How do I measure whether a chatbot helps?
Track conversations that become booked calls or applications, compared with the contact form over the same period. Volume alone can be misleading.
What should happen when a chatbot cannot answer?
It should say so plainly, offer to connect the visitor with a loan officer, collect contact details with clear consent if the visitor agrees, and create a follow-up task in your CRM. A fallback that guesses is worse than one that hands off honestly.
Sources and further reading
Talk through chatbot and inquiry options
We will look at your current contact path and discuss whether a chatbot integration makes sense, what it would involve and what guardrails it needs.
Discuss your options